Choosing employee health coverage involves more than selecting the plan with the lowest monthly premium. Small business owners need to balance budget limits, employee access to care, and the administrative work required to support enrollment. A practical starting point is understanding how group health insurance works for small employers before reviewing plan quotes.
Plan availability, pricing, network access, and participation rules can differ by insurer, workforce location, and state. Comparing options early gives employers time to identify trade-offs, ask informed questions, and communicate a clear decision to employees.
Why Comparing Health Plans Matters
A lower-premium plan may shift more costs to employees through a higher deductible, coinsurance, or narrower provider network. For example, one plan may have a lower payroll cost but require employees to pay substantially more before coverage begins. In contrast, another may cost more each month but provide predictable office visit copays and broader access to local providers.
Comparing plans side by side helps employers see how the benefit design affects recruiting, retention, employee satisfaction, and the business budget. The goal is not to find one universally best plan. It is to find a sustainable option that fits the workforce.
Set Benefits Goals and Review Employee Needs
Before requesting quotes, establish a monthly employer contribution budget, decide whether to contribute toward dependent coverage, and identify the features that matter most. A business focused on controlling payroll costs may prefer a different structure than one competing for hard-to-fill roles.
Use an anonymous survey to ask employees about priorities such as doctor choice, lower deductibles, behavioral health care, telehealth, or prescription affordability. Do not request personal medical details. Consider the practical needs of employees with families, hourly schedules, remote work arrangements, or residences in multiple states.
Photorealistic small business owner and employee reviewing health insurance plan comparisons together at a bright office table, with printed documents, a laptop, and a calculator visible; warm golden-hour light through the window, natural directional lighting, soft shadows, and a thoughtful collaborative mood.
Compare Plan Types and Costs
Small employers may encounter several common plan structures. An HMO typically emphasizes care within a defined network. A PPO may offer greater flexibility in using out-of-network providers, usually at a higher cost. An EPO generally covers nonemergency care only within its network. High-deductible plans can have lower premiums and may be compatible with a health savings account when federal requirements are met.
Review each proposal using the same set of details:
- Employer premium contribution and employee payroll deduction.
- Annual deductible and annual out-of-pocket maximum.
- Copays for primary care, specialists, urgent care, and emergency services.
- Coinsurance that applies after a deductible is met.
- Costs for employee-only, spouse, child, and family coverage.
- Any enrollment, administration, or technology fees.
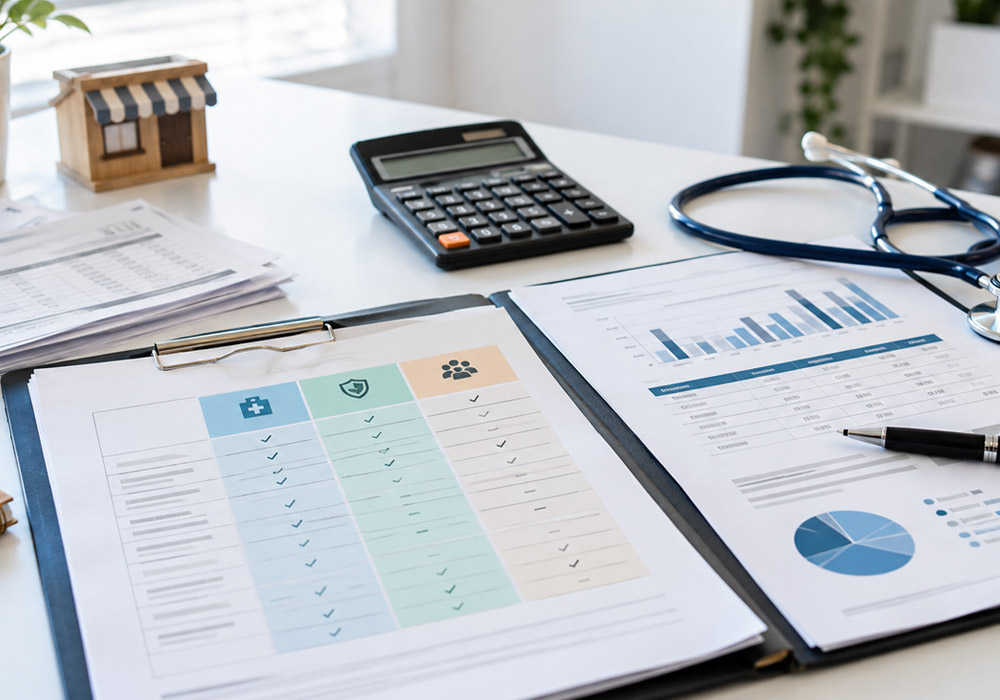
A simple comparison list is often more useful than a premium-only spreadsheet. For each plan, write down the premium, deductible, out-of-pocket maximum, office visit cost, prescription terms, and the breadth of the available network.
Check Networks and Prescription Coverage
A plan is only useful when employees can reasonably access care. Ask employees to verify whether their doctors, preferred hospitals, urgent care locations, specialists, and behavioral health providers participate in the network. Provider directories can change, so employees should confirm directly with the carrier or provider before enrolling.
Also compare prescription formularies, pharmacy networks, mail-order options, drug tiers, prior authorization requirements, and specialty medication policies. These details can make a meaningful difference for employees who take ongoing medications.
Review Coverage Options, Eligibility, and Taxes
Traditional small-group coverage is one approach, but some employers also evaluate high-deductible plans, eligible health savings account arrangements, or health reimbursement arrangements. The right fit depends on workforce needs, employer budget, and the business’s ability to manage communications and administration.
Eligible businesses can also explore SHOP coverage options for small employers, which may allow employers to offer health or dental coverage and work with a registered agent or broker. Employers should verify the rules that apply to their business and location before relying on any assumption of eligibility.
Employee counts and full-time equivalent calculations can affect responsibilities and potential tax treatment. Businesses considering the credit should review the requirements for the small business health care tax credit with a qualified tax professional. Eligibility can depend on factors including workforce size, average wages, employer premium contributions, and the type of coverage offered.
Build an Enrollment Process and Avoid Mistakes
Create a timeline that includes quote review, decision-making, employee communication, elections, payroll setup, and confirmation of effective dates. Give employees a plain-language summary that explains what changed, what the company contributes, and where to ask questions.
Common mistakes include selecting a plan based only on premiums, overlooking family coverage costs, assuming doctors are in-network, using outdated plan documents, and waiting until the final days before renewal. Store elections and waivers securely, and confirm deductions before the first payroll with the new coverage.
2026 Comparison Checklist
- Count eligible employees and confirm the renewal date.
- Set employer and employee contribution amounts.
- Compare plan type, deductible, copays, coinsurance, and out-of-pocket maximum.
- Check provider networks, mental health services, telehealth, and prescriptions.
- Review dependent coverage costs and participation requirements.
- Prepare questions for the insurer, broker, benefits adviser, and tax professional.
Common Questions From Small Business Owners
Does a small business have to offer health insurance?
Requirements can depend on employer size and applicable federal and state rules. Many smaller employers choose whether to offer coverage, while larger employers may have additional responsibilities.
Should an employer pay the full premium?
Not necessarily. Employers may pay a fixed percentage or dollar amount, and may use different contribution levels for employee-only and dependent coverage.
What matters more, a low premium or a low deductible?
Neither measure tells the full story by itself. Compare the yearly premium cost with expected out-of-pocket costs, provider access, and prescription needs.
When should a business start comparing plans?
Begin several months before the renewal or enrollment date whenever possible. Extra time makes it easier to compare options, communicate changes, and correct enrollment issues.
Conclusion
A strong health plan comparison considers cost, access, employee priorities, and administrative effort simultaneously. The best option in 2026 is the one that supports the business budget while giving employees coverage they can understand and use.